Special Needs Trusts in Raleigh, North Carolina
Provide for Your Child With Special Needs Without Putting Their Benefits at Risk
Leaving money directly to a loved one with a disability can cost them the Medicaid and SSI they rely on. A special needs trust is how you give them more - without taking away what they already have.
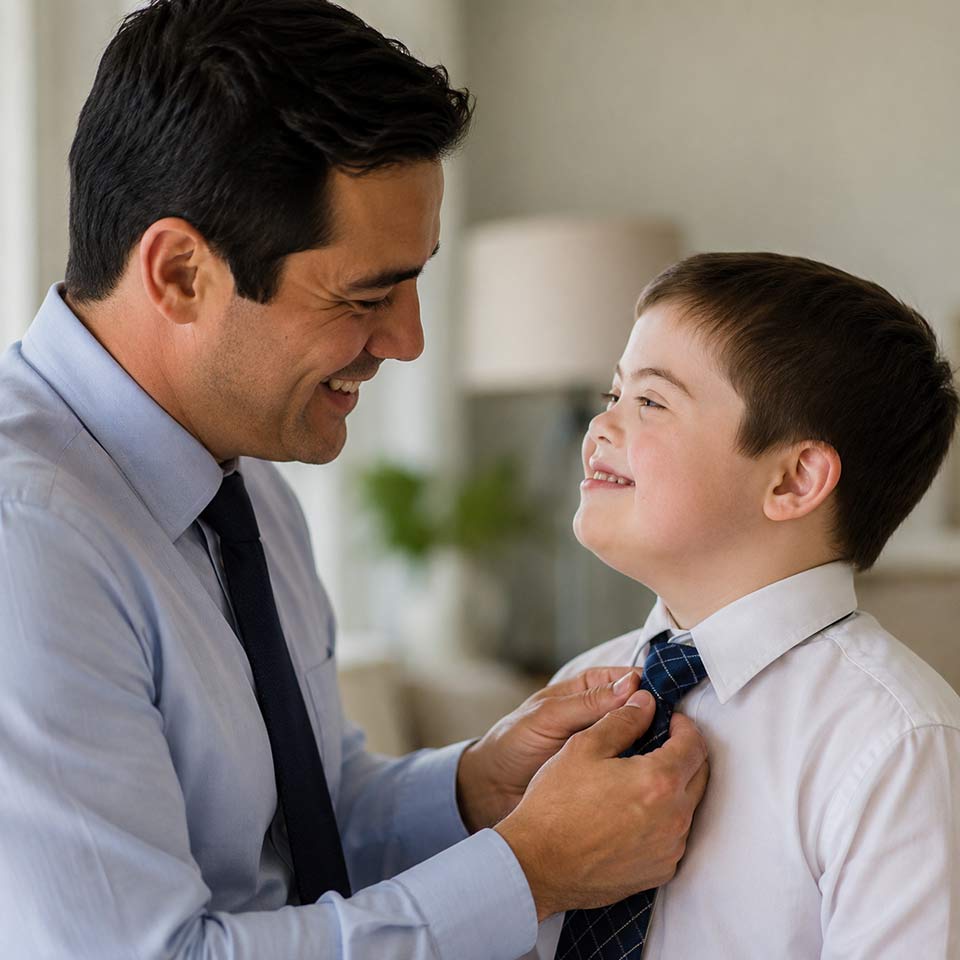
What a Special Needs Trust Actually Does
Medicaid and SSI are means-tested - qualify for them and you generally can't have more than a few thousand dollars to your name. So when a parent leaves an inheritance straight to a child with a disability, that gift can push them over the limit and end the benefits the family spent years securing.
A special needs trust solves that. Instead of going to your child directly, the money goes into a trust. A trustee you choose holds it and spends it on the things benefits don't cover - therapy, education, travel, a phone, a caregiver, the small comforts that make a life fuller. Because your child never owns the funds outright, the trust doesn't count against their eligibility.
The result: your child keeps Medicaid and SSI, and they also have a cushion for everything those programs leave out.
First-Party vs. Third-Party Trusts
There are two kinds, and the difference matters:
Funded by family
Funded with someone else's money - usually a parent's or grandparent's - as part of an estate plan. There's no Medicaid payback, so whatever is left at your child's death passes to the people you name.
The beneficiary's own money
Holds money that already belongs to the person with a disability - often a personal-injury settlement or a direct inheritance. It protects benefits the same way, but Medicaid must be repaid from what's left.
I build both, and I'll tell you plainly which one fits your situation.
Is This Right for Your Family?
A special needs trust is usually the right move if:
You have a child or family member who receives, or may someday need, Medicaid or SSI.
You want to leave them an inheritance without it ending their benefits.
A loved one with a disability is about to receive a settlement or a direct inheritance.
You want a trusted person, not the state, deciding how that money helps them.
If a relative has already named your child in their own will, that's worth a conversation soon - a well-meaning gift left the wrong way can do real harm.
Common Questions
Will an inheritance really disqualify my child from SSI or Medicaid?
It can. Both programs cap how much a recipient can own. A direct gift of even a modest amount can put them over the limit and suspend benefits until the money is spent down. A special needs trust avoids that because your child never owns the funds outright.
What can the trust pay for?
Things the public benefits don't cover - therapies, education, transportation, technology, recreation, a caregiver, household items, and many other quality-of-life expenses. The trustee handles distributions so they supplement benefits rather than replace them.
Who should be the trustee?
Someone responsible who understands your child and the benefit rules - often a family member, sometimes a professional trustee, frequently both working together. We'll talk through who fits and build in backups so there's never a gap.
When should we set it up?
Before it's needed. Most families fold a third-party special needs trust into their estate plan now, so it's ready and funded whenever it's required. If a settlement or inheritance is already on the way, it's time-sensitive - call sooner rather than later.
Let's Protect Your Child's Future
You'll work with me directly, from our first conversation to the day you sign. That first conversation is free and there's no pressure - tell me about your family, and I'll tell you what actually makes sense for you.